Viw Magazine

The Times


.

The shocking truth about insurance. We pick bad policies even with good information

  • Written by: Justin Malbon, Professor of Law, Monash University
Even with a simple choice between an obviously good product and an obviously bad one, many people choose wrong. Shutterstock

The Financial Services Royal Commission has highlighted the astonishment and anger of some customers who’ve had their insurance claims rejected.

Some assumed wrongly their policy covered them for losses from their heart attack or cancer. Others were angry and frustrated that their home contents insurance didn’t cover losses from floods.

When you take out insurance you are buying a promise. The insurer promises to pay for losses arising from the event mentioned in the policy; be it fire, robbery, flood or something else.


Read more: What is flood insurance and why the system is broken: 6 questions answered


It would be reasonable to think that a sensible person would know what that promise was before he or she paid the premium.

But that assumes a sensible person can understand the words used in the policy.

Federal legislation requires insurers to produce a product disclosure statement (PDS) and make it available to potential buyers.

They are not always easy to find on the insurer’s website and, even when they can be found, are usually long and complex.

No less a body than the Insurance Council of Australia has acknowledged that the exclusions and limits in the statements are often poorly understood.


Read more: Forcing insurers to reveal rejected claims a win for consumers


To overcome this problem, it has been mandatory since 2012 for home contents insurers to also provide a shorter two-page “key fact sheet” (KFS).

It outlines in simpler language which events the policy does, and does not, cover.

We undertook a study, funded by the NSW Financial Rights Legal Centre to find out if a KFS is more likely to nudge consumers towards making rational buying choices than simply providing a PDS.

Does a ‘key fact sheet’ help?

We found that, even in highly idealised conditions, the KFS wasn’t a standout success.

The study involved 406 randomly chosen participants across Australia. They were asked to consider buying a hypothetical home contents insurance policy.

We provided them various choices between buying a good, okay or bad policy. They were not told the policies varied in quality. The only information they had about each policy was a PDS or a KFS, or both, we designed.

They could also choose not to buy a policy.


Read more: Royal commission scandals are the result of poor financial regulation, not literacy


We told them that after they decided on their purchase, a computer simulation might signal that an event, like a robbery or fire, would happen over the following 12 months - or that nothing would happen. If the simulator signalled a bad event, and they hadn’t bought insurance that covered them for it, they would lose a “bonus payment”.

The good policy included cover for fire and explosion but excluded “damage that occurs within 72 hours of the beginning of your policy”. The bad policy also covered fire and explosion but excluded “fires igniting within or outside the premises” – in other words it effectively excluded any cover for fire.

The inclusions and exclusions were not buried in fine print but set out clearly in both documents.

Here are the findings for when we asked people to choose between the good policy and the bad policy:


The best outcome was when participants were offered only a short KFS and not the longer PDS. In this scenario 76% of participants opted for the good policy.

Yet even in this most ideal circumstance – a simple choice between an obviously good product and an obviously bad one on the basis of a clear two-page document – about 10% still chose the bad product and 14% bought no insurance at all.


Read more: People on low incomes are sacrificing basic goods to take out insurance


Disturbingly, the worst outcome was when participants were presented with both the short KFS and the longer PDS. It was even worse than with the disclosure statement only.

When participants were required to choose between three products, the proportion choosing the better product declined markedly. Using the KFS alone, only 41% chose the best product.

The take-home message is that although being presented with the KFS appears to be marginally better than being presented with the PDS, or even both, it is far from a panacea.

Time to rethink the onus on us

These findings, along with other research on the lack of consumer comprehension of insurance terms and conditions, ought to prompt a rethink about putting the onus on consumers to make the best choices on the basis of the information available to them.

The government might instead consider mandating standard terms for consumer insurance products across the entire industry.

The inclusions and exclusions for all home contents policies, for example, would be the same. And also for motor vehicle, travel and other forms of insurance.


Read more: Do we really need funeral insurance?


Consumers could be offered a choice between gold standard cover, which would provide the most cover, and silver and bronze, which would offer less.

By mandating standard terms, consumers would have less anxiety about what is buried in the detail of their policies.

It would mean insurers have to compete on price, rather than confusing consumers by making products difficult to compare.

Justin Malbon received funding from the Financial Rights Legal Centre. He is an independent member of the Comminsure Claims Review Panel. He is also a member of the Superannuation Complaints Tribunal.

Harmen Oppewal received funding from the Financial Rights Legal Centre and the Australian Research Council.

Authors: Justin Malbon, Professor of Law, Monash University

Read more http://theconversation.com/the-shocking-truth-about-insurance-we-pick-bad-policies-even-with-good-information-103515

From the Racetrack to the Wrist: The Sports Partnerships Behind Richard Mille

Few watchmakers have tied their identity to elite sport as closely as Richard Mille. Founded in 2001, the brand set out to apply the think...

Blocked Drains in Sydney Apartments: Who Is Responsible Under NSW Strata Law?

A blocked drain in a house is annoying but easy to understand. The pipes are on your land, so the problem is yours. In an apartment or tow...

Best HCM Software for Growing Australian Businesses

There's a clear moment in the life of a fast-growing Australian company. The spreadsheet that once tracked leave starts breaking. Onboardi...

How Does Thematic Investing Combine Convenience With Direct Ownership?

Retail investors increasingly seek ways to access long-term structural trends without the complexity of picking individual stocks. The major...

Why We Trust What Other People Already Like: Social Proof in the Age of Instagram

Long before you read a caption or inspect an image, you have already processed the number sitting underneath the post. Forty likes and 12...

Google Updates 2026: A Practical SEO Checklist for Australian Businesses

  Google updates 2026 are on the minds of businesses that rely on search to reach customers, whether they sell software, gadgets, games or ...

What to Add to Your Weekly Diet for Stronger, Glossier Strands

Achieving thick, vibrant hair requires more than just high-quality shampoos and topical serums. Real hair vitality starts from within, drive...

How to Reverse Sun Damage and Restore Moisture to Your Hair

Australia's harsh summer sun takes a heavy toll on our tresses, leaving them dry, brittle, and prone to breakage. While many of us remembe...

How to Build a Daily Hair Care Routine for Stronger, Shinier Strands

Achieving lustrous, resilient hair requires consistent daily care rather than occasional expensive treatments. While advanced clinical opt...

What to Do for Fine Hair to Instantly Boost Volume

Fine, flat hair often feels like a daily styling challenge, leaving many searching for ways to inject life and bounce into limp locks. While...

Why Melbourne Buyers Choose Loose Sapphires for Custom Engagement Rings

An engagement ring often starts as a finished image: a stone in a setting, photographed from the perfect angle. But some couples prefer to...

How to Clear a Deceased Estate: A Gentle, Practical Guide for Sydney Families

Losing a loved one is hard enough. Then, often within weeks, families are faced with the task of sorting through a lifetime of belongings...

NBN Not Working? Common Causes and What to Do Before Calling a Technician

There's never a good time for the internet to drop out. It always seems to happen in the middle of a work call, halfway through a movie or...

Water Tanks: What to Consider Before Choosing One for Your Property

Define the purpose of the tank Water tanks can serve different purposes, so the first step is to identify what the stored water will be u...

Off-Road Caravan for Sale: What to Look for Before You Buy

Buying a caravan is a significant investment. So, it is worth looking beyond the price tag and choosing a dealer that understands what you...

How Split Corrugated Conduit And Solar Conduit Support Better Cable Protection

Why Cable Protection Starts With The Application Wiring can encounter movement, abrasion, moisture, heat and physical contact depending o...

Can You Increase Your Income with Duplex and Dual Occupancy Builds?

A dual occupancy build is when 2 independent homes are constructed on a single block of land. They can either share a wall, as with a dupl...

Choosing Shutters and Blinds for Different Rooms in a Melbourne Home

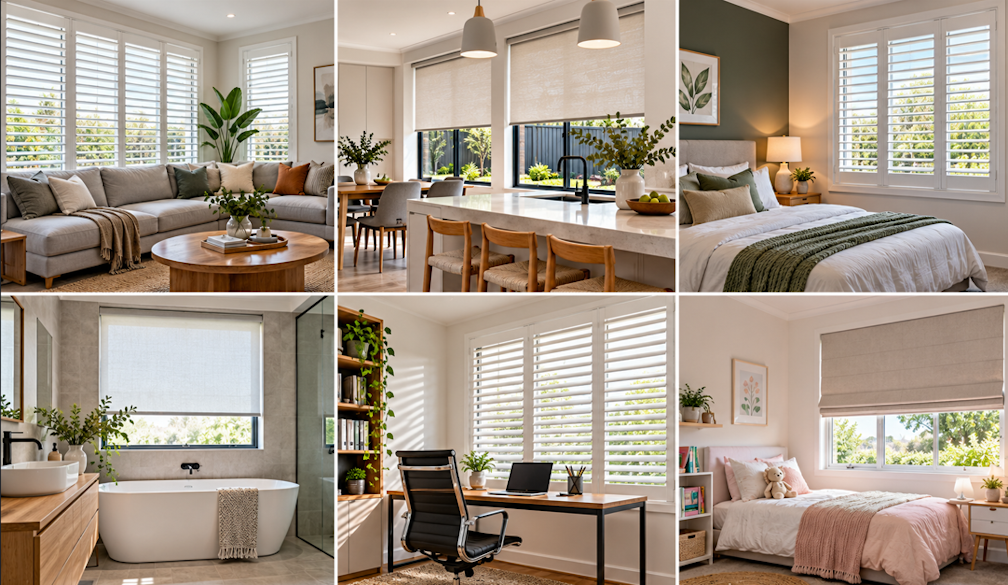
Start With the Function of Each Room For homeowners comparing window coverings, shutters and blinds can be assessed by looking at light c...

How Property Conveyancing In Melbourne Helps Buyers And Sellers Navigate A Property Transaction

What Property Conveyancing Involves In Melbourne Buying or selling a property involves more than signing a contract and arranging finance...

Planning Bottle Label Printing for Different Product Applications

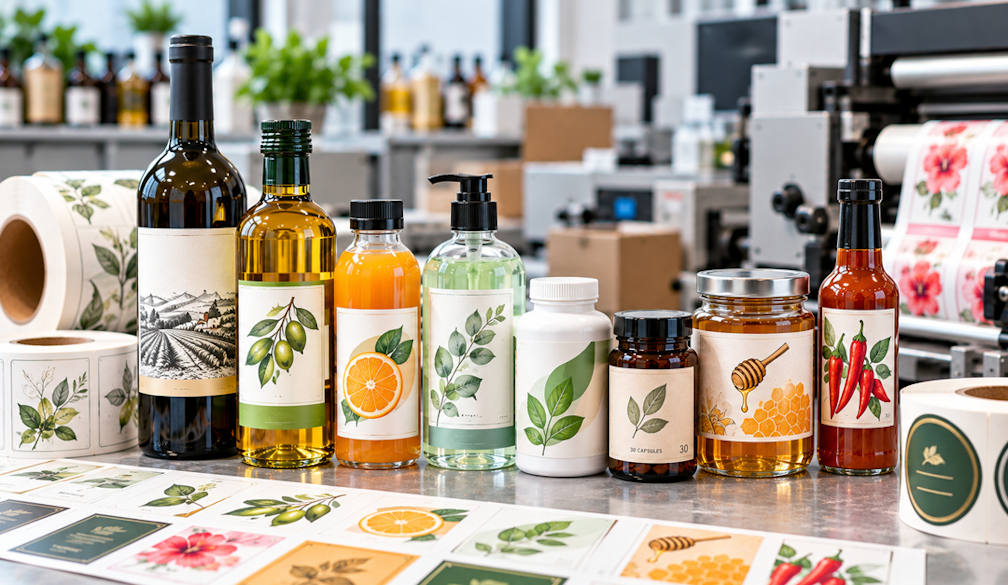
Bottle Branding Across Different Industries When businesses need packaging or printed containers developed for a particular application, ...

Why Corten Is Used for Distinctive Outdoor Steel Applications

Understand the weathering process Outdoor steel can serve both a functional and visual purpose, particularly when a project calls for a w...

Trailers in Melbourne: How to Choose the Right Box Trailer for Your Needs

Comparing Trailer Types in Melbourne The right trailer depends on what needs to be transported and how the trailer will be used. Buyers com...

How a Livestock Identification and Traceability System Supports Smarter Cattle Management

Why Identification Matters Beyond Basic Herd Records Modern cattle management depends on having reliable information about where animals ...

Choosing A Locksmith Melbourne For Residential Security Needs

Why The Right Locksmith Matters Finding a reliable locksmith Melbourne homeowners can contact involves more than locating someone who can...

hacklink Herabettaraftarium24canlı maç izleselcuksportstaraftarium24TrBettaraftarium24taraftarium24justin tvvpnStreamEasttaraftarium24free books downloadzlibraryzlibjustin tvtaraftarium24taraftarium24maç izletaraftarium24taraftarium24taraftarium24jojobetjojobetjojobetgiriş jojobetjojobetmygiftFutemaxPelota Libretaraftarium24meritbettaraftarium24free betsGalabetGalabetviljo kasinotStreamEastcasibomGalabetCrackStreams1xbetjustin tvdizipalbets10deneme bonusu veren sitelerdizipalhttps://bahisfair-gunceladres.world/tr/jojobetdeneme bonusu veren sitelerDeneme bonusu veren sitelerDeneme bonusucasibomcasibomSahabetvdcasinojojobettaraftarium24vipparkselcuksportstaraftarium24canlı casino sitelerijojobetcasinolevantcasinolevantcasinolevantcasinolevantcasinolevantcasinolevantcasinolevantcasinolevanttaraftariumgalabet girisbetciogalabetjojobetholiganbetjojobethacklink panelgalabetiptv izleTotalSportgalabettarafbet