Viw Magazine

The Times


.

Requiring firms to only sell financial products we can use is good, but not enough

  • Written by: Kevin Davis, Professor of Finance, University of Melbourne
Shutterstock

The government’s financial system inquiry, on which I sat, reported five years ago.

It recommended that the creators of financial products be subject to a design and distribution obligation (DDO), which would mean the products they sold had to not only make money for them, but also meet the needs of the people buying them.

An insurance policy that couldn’t be claimed on would fail the test, as would a product that charged fees for advice that wasn’t given, as would any number of products later detailed in the 2018 report of the financial services royal commission.

It’s the first half of 2020, and the Australian Securities and Investments Commission is seeking input into how the obligation will work. It has asked for comments by March 11.

Requiring products to be useful is good…

There ought to be nothing controversial about the idea. It reflects the fundamental premise upon which the free market economy is founded – that transactions should provide gains to both the seller and buyer.

Reputable financial institutions, seeking to meet community expectations, ought to already meet such obligations, although they are likely to incur some (hopefully minor) administrative costs.

However, as history and the royal commission have reminded us, even reputable institutions’ procedures can go awry and lead to badly designed products that exploit consumers.


Read more: CommInsure proves the need for a banking royal commission


Less reputable firms exploit consumers anyway, leading to a race to the bottom in terms of product quality.

…but not enough

Unfortunately, even if a financial product meets the DDO requirements, which means it is suitable for its intended consumers, it can be a bad purchase for consumers who aren’t aware of its true worth. Retail customers who overpay for a “suitable” product can lose just as much (if not more) as those being sold one that’s unsuitable.

Many financial products (actually, most financial products) have characteristics that make them hard to value accurately. When product outcomes depend on future events – as do insurance products – accurate valuations can be almost impossible even for customers who are financially literate.

For example a consumer might assume that there is a 10% chance of an event happening, when the true probability is less than 1%. Not only would they overpay on insurance (perhaps repeatedly), they would be unlikely to ever know about it.

It’s hard to tell when prices are bad

Suppose a producer can supply a financial product profitably for any price over $6. Suppose that buying it for any price under $8 would would benefit the consumer, but that the consumer is unable to tell what it is really worth.

Since the supplier’s profits increase as the selling price increases, what is there to stop the supplier increasing the price to more than $8 and harming consumers, in part because some would never get the product?

Standard answers talk about competition, disclosure, financial advice and financial education.

But if consumers don’t have the information they need (or the time they need) to do the calculations, what’s likely to happen instead is that competition will cut the worth of the products in ways that are not obvious to consumers.

As important as disclosure, advice and education are, they haven’t been able to stop this happening in the past.

What we are seeing are first steps

Plans by the Australian Prudential Regulation Authority to make banks and other deposit-taking institutions designate an accountable executive as responsible for the “end-to-end” creation and delivery of each product under a Bank Executive Accountability Regime (BEAR) would be an important step.

The government has announced plans to extend it to all financial institutions, making it a FAR (Financial Accountability Regime).

But there is nothing in either the BEAR or FAR rules that that would require the executives to price their products fairly.


Read more: HILDA Survey reveals striking gender and age divide in financial literacy. Test yourself with this quiz


DDO’s, together with the Securities and Investments Commission’s new temporary banning powers, should help to rid the financial sector of the most egregious types of consumer abuse. But will they do nothing to prevent profit seeking institutions setting prices for “suitable” products that cause poorly informed consumers harm.

It is not clear what could, short of instilling a sense of “fairness” into corporate cultures. While welcome, DDO’s are only the start.

Kevin Davis does not work for, consult, own shares in or receive funding from any company or organisation that would benefit from this article, and has disclosed no relevant affiliations beyond their academic appointment.

Authors: Kevin Davis, Professor of Finance, University of Melbourne

Read more https://theconversation.com/requiring-firms-to-only-sell-financial-products-we-can-use-is-good-but-not-enough-131887

Why Professional Duct Cleaning Matters for a Cleaner Indoor Environment

A ducted heating or cooling system moves air through a network of return air ducts, individual duct lines and other components. Over time...

Brisbane’s Subdivision Rush Causes Concern Around Strata Survey Delays

To increase the housing supply across Brisbane, Queensland has put sweeping legislative changes into effect. As a result, residential prop...

First Trip to the USA? Phone and Data Tips Before You Board

The first hour in an American airport can be busier than the flight. You might need to book a ride from LAX, message a hotel in Manhattan ...

Caravan Dealers in Sydney and Melbourne Report Fuel Efficiency Back as Top Selling Point

Economic pressures are mounting as fuel prices continue to fluctuate; household budgets have never been tighter. As a result, caravan dealer...

Why a Child's Foot Is Meant to Change Shape as They Grow

Most children under three have flat feet, and most develop an arch by around age six, according to the Royal Children's Hospital in Melbou...

Workplace Safety Essentials Every Australian Employer Should Know

Safety is one of those topics that sends some business owners reaching for the snooze button. It conjures images of thick policy manuals, en...

A Beginner's Guide to Australia's Favourite Asian Comfort Foods

There is a particular kind of Australian childhood memory that involves a fish and chip shop, a paper bag and a deep-fried dim sim with a ge...

Signs Your Relationship Needs More Than Just a Date Night

Date nights get a lot of credit. Book a babysitter, go somewhere nice, put the phones away and reconnect. And for plenty of couples going th...

Flooring Trends Australian Homeowners Are Loving This Year

Floors are the one part of a renovation you walk on every single day, yet they are often the last thing people think about. Paint colours ge...

Ask ChatGPT Who the Best [Your Trade] in Your Area Is. Then Ask Yourself Why It Isn't You.

Your next customer may never see your website. They'll ask an AI, get a short list of names, and pick one. Here's how to find out if you'r...

If Your Labour Hire Provider Isn't Licensed, Guess Who Else Pays the Fine?

Most business owners assume licensing is the provider's problem. In South Australia and several other states, it's theirs too. Here's how to...

Gippsland by Offroad - Victoria's Hidden Gems

New to Gippsland and want to get to know her beauty better? Off-road caravans open up parts of this region, with its stunning landscape and ...

Police Want to "Have a Quick Chat". Here's What a Defence Lawyer Wishes You Knew First.

It usually starts politely: a phone call, a card in the letterbox, an invitation to "come in and clear something up". What you do next mat...

Ever Wondered Why Cosmetic Clinics Are So Careful About What They Say Online?

No prices, no product names, no glowing influencer reviews. If cosmetic clinic marketing has ever felt a little vague, there's a good reas...

Honouring Faith and Family: Understanding Traditional Funeral Rites in Australia

Australia's funerals are as varied as its people. On a single day in any capital city, you might find a Greek Orthodox service with its open...

Instant Tan vs Gradual Tan vs Developing Tan: Which One Suits Which Occasion

Walk into the self tan aisle in any Australian pharmacy and three product categories stare back at you. Instant tan promises colour you ca...

Why Western Sydney Has Become Australia's Most Watched Commercial Property Hotspot

Drive west along the M4 or out towards Badgerys Creek and the change is hard to miss. Paddocks that sat untouched for decades are now dotted...

Planning a Festival Bar That Can Handle a Victorian Crowd

If you’ve ever worked the bar at a Victorian festival, you’ll know the weather isn’t really what gets you. The real crunch comes right aft...

From the Racetrack to the Wrist: The Sports Partnerships Behind Richard Mille

Few watchmakers have tied their identity to elite sport as closely as Richard Mille. Founded in 2001, the brand set out to apply the think...

Blocked Drains in Sydney Apartments: Who Is Responsible Under NSW Strata Law?

A blocked drain in a house is annoying but easy to understand. The pipes are on your land, so the problem is yours. In an apartment or tow...

Best HCM Software for Growing Australian Businesses

There's a clear moment in the life of a fast-growing Australian company. The spreadsheet that once tracked leave starts breaking. Onboardi...

How Does Thematic Investing Combine Convenience With Direct Ownership?

Retail investors increasingly seek ways to access long-term structural trends without the complexity of picking individual stocks. The major...

Why We Trust What Other People Already Like: Social Proof in the Age of Instagram

Long before you read a caption or inspect an image, you have already processed the number sitting underneath the post. Forty likes and 12...

Google Updates 2026: A Practical SEO Checklist for Australian Businesses

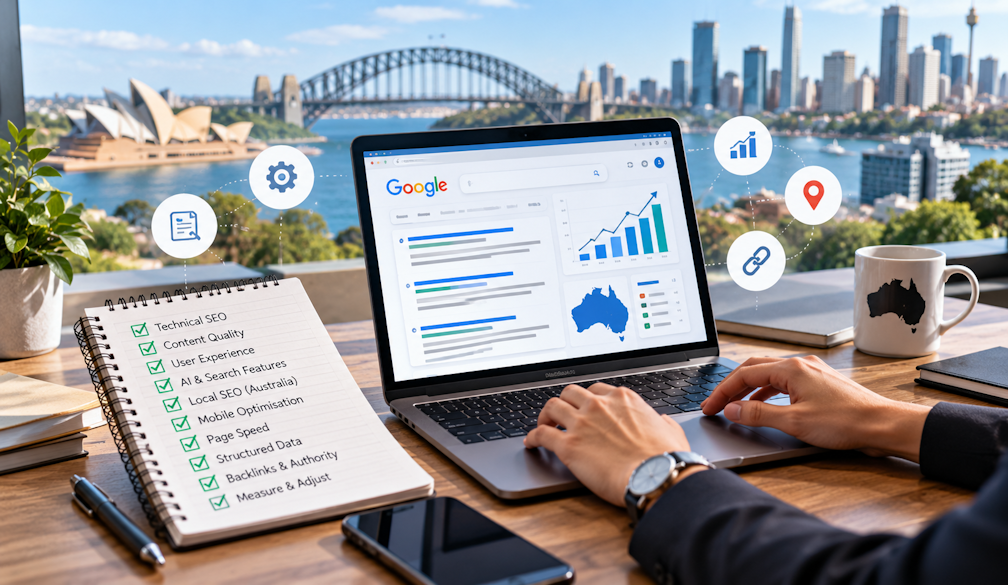
  Google updates 2026 are on the minds of businesses that rely on search to reach customers, whether they sell software, gadgets, games or ...

hacklink Herabettaraftarium24taraftarium24selcuksportstaraftarium24TrBettaraftarium24justin tvtaraftarium24vpntaraftarium24free books downloadzlibraryzlibjustin tvvipparkCrackStreams1xbetjustin tvdizipalbets10deneme bonusu veren sitelermarsbahishttps://bahisfair-gunceladres.world/tr/jojobetdeneme bonusu veren sitelerDeneme bonusu veren sitelerDeneme bonusucasibomcasibomGüvenilir slot sitelerivdcasinojojobettaraftarium24vipparktaraftarium24taraftarium24giftcardmall/mygiftjojobetcasinolevantcasinolevantcasinolevantcasinolevantcasinolevantcasinolevantcasinolevantcasinolevanttaraftariumvipparkbetciovipparkholiganbetmarsbahismeritkinghacklink panelpadisahbet güncel girişiptvCrackStreamsgalabet güncel girişjojobetjojobetbetparkstreameastnon gamstopBetimtaraftarium24casino sitelerigrandpashabetdeneme bonusu veren siteler